The Traditional IRA
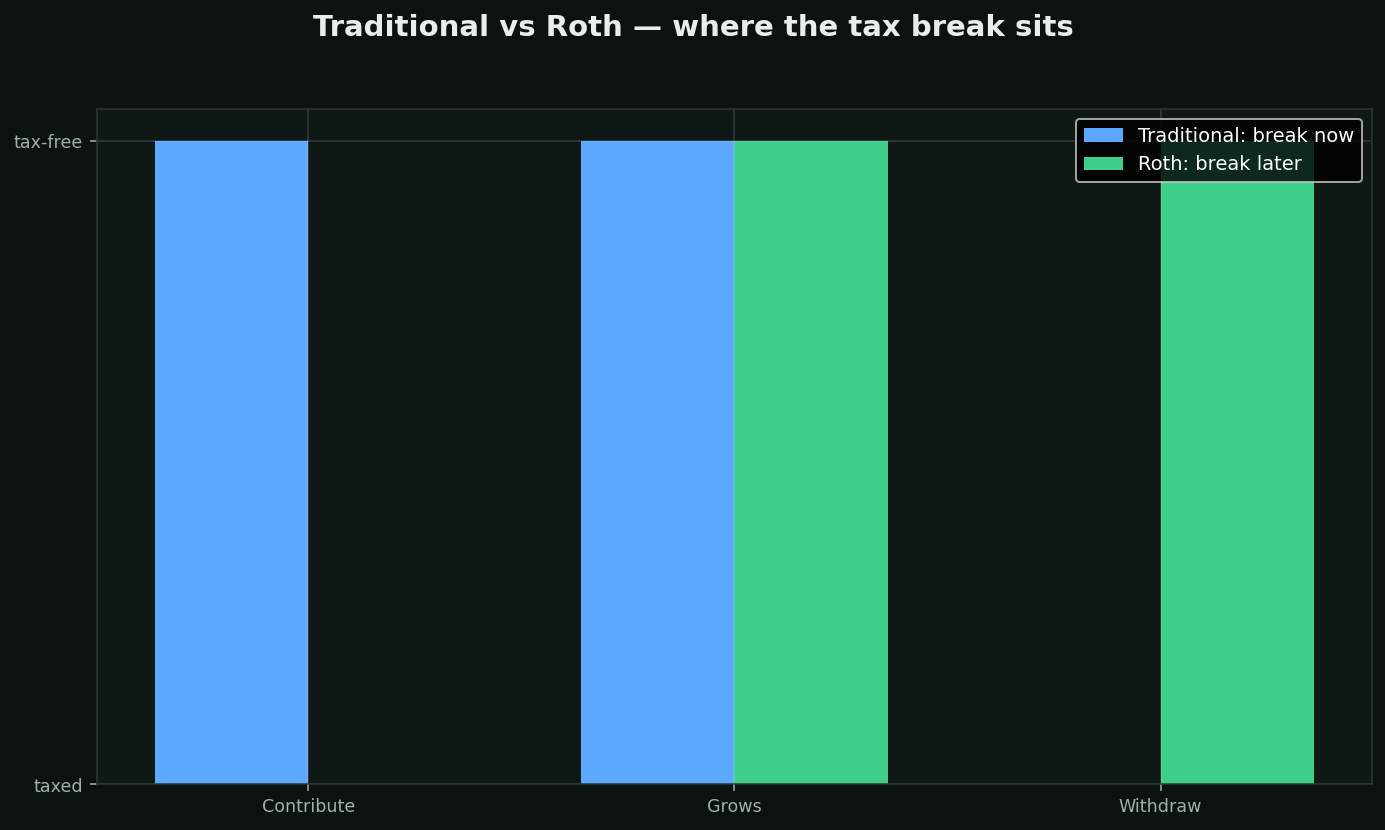
What it is: the mirror image of a Roth. You contribute money BEFORE tax (often deductible), it grows untaxed, and you pay ordinary income tax on everything you withdraw.
Why it matters: the deduction is real money back in your pocket today. If you are in a high bracket now and expect a lower one in retirement, deferring is the better arithmetic.
The mechanics:
• Deductibility phases out if you (or a spouse) have a workplace plan and earn above a threshold.
• Withdrawals before 59½ generally mean tax *and* a penalty.
• Required minimum distributions eventually force money out, whether you need it or not.
The honest answer to 'which one': nobody knows their future bracket. Splitting across both is a hedge, not a cop-out.