Roth vs Traditional, the actual maths
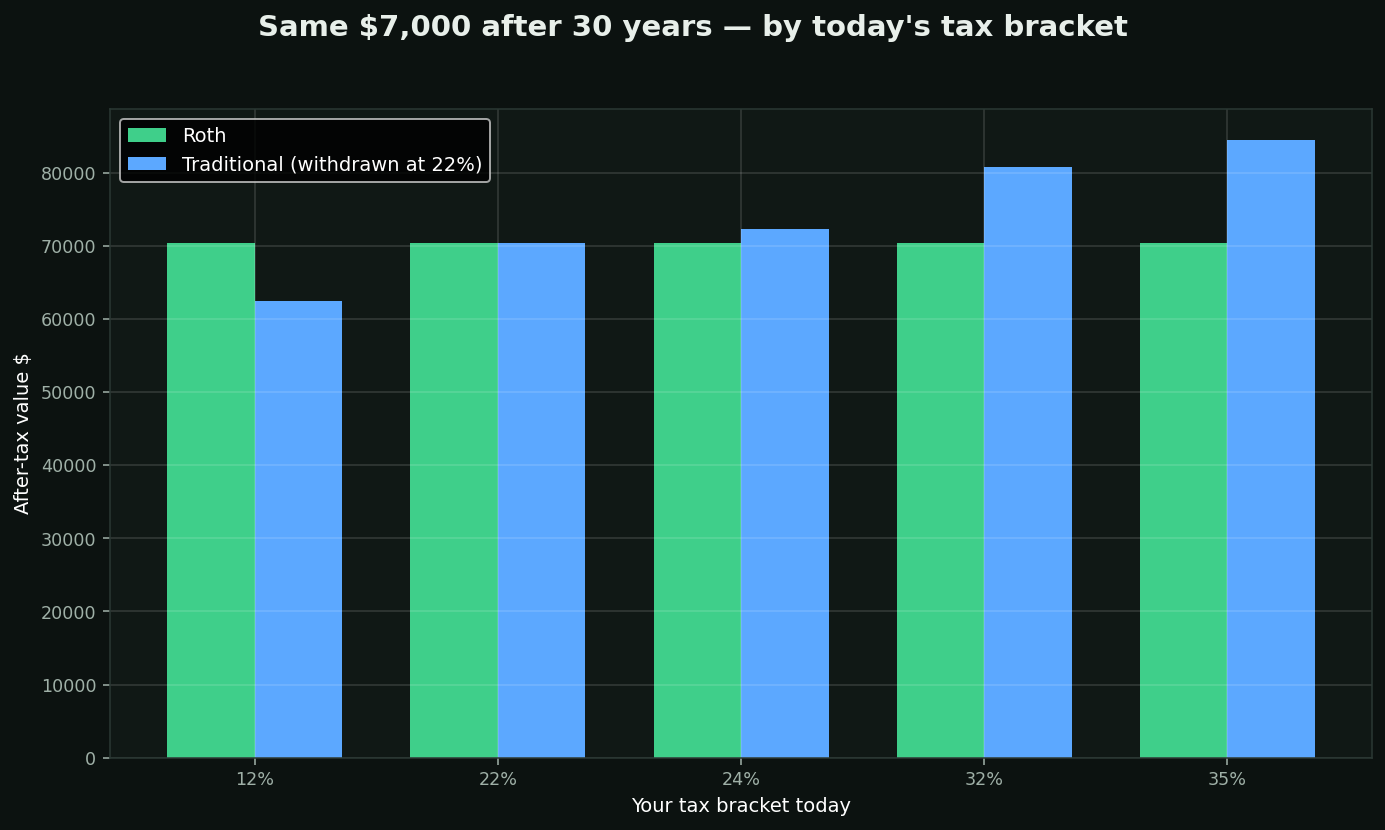
The rule people repeat: 'Roth if you'll be in a higher bracket later.' True, but it hides the real mechanism.
What actually happens: a Traditional deduction lets you invest MORE up front — the tax you did not pay is also working for you. Whether that beats tax-free growth depends only on your rate now versus your rate at withdrawal.
Chart (illustrative): $7,000 invested for 30 years at 8%, withdrawn in a 22% bracket. When today's bracket is higher than 22%, the Traditional wins. When it's lower, the Roth does.
What the chart cannot show:
• Roth has no required withdrawals, which matters for estates
• Tax law changes over 30 years
• Your future bracket is a guess, not an input
That uncertainty is why splitting is common.