The cash flow statement
Why it is the one to trust: profit is an opinion shaped by accounting choices. Cash is a fact. This statement reconciles the two.
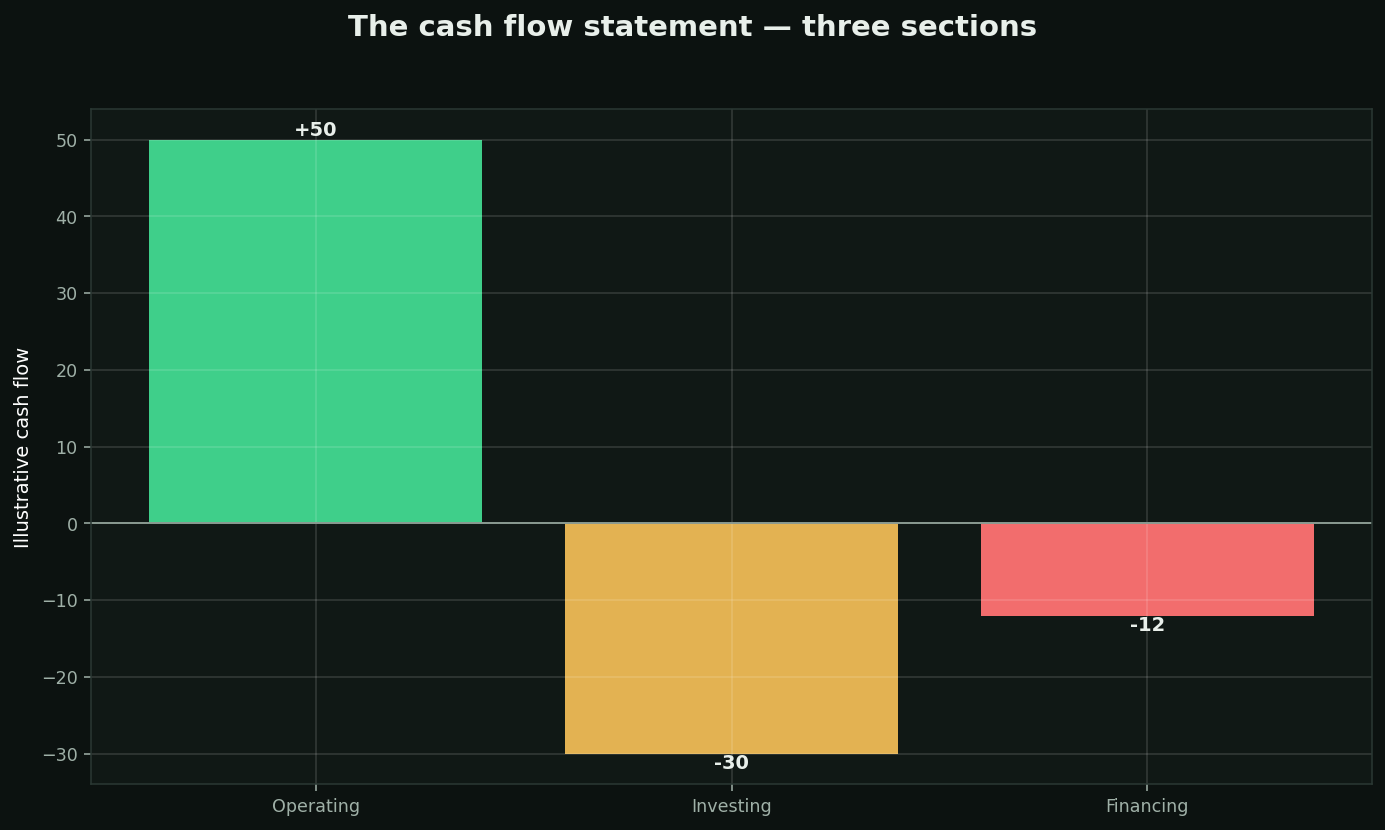
Three sections:
• Operating — cash from actually running the business. Should be positive and should roughly track net income over time.
• Investing — buying and selling long-term assets. Usually negative for a growing company, and that is healthy.
• Financing — borrowing, repaying, dividends, buybacks
The single best red flag in fundamental analysis: net income rising while operating cash flow falls. That gap is where aggressive revenue recognition and ballooning receivables show up, and it precedes a great many blow-ups.
Free cash flow = operating cash flow minus capital spending. It is what actually funds dividends and buybacks.